

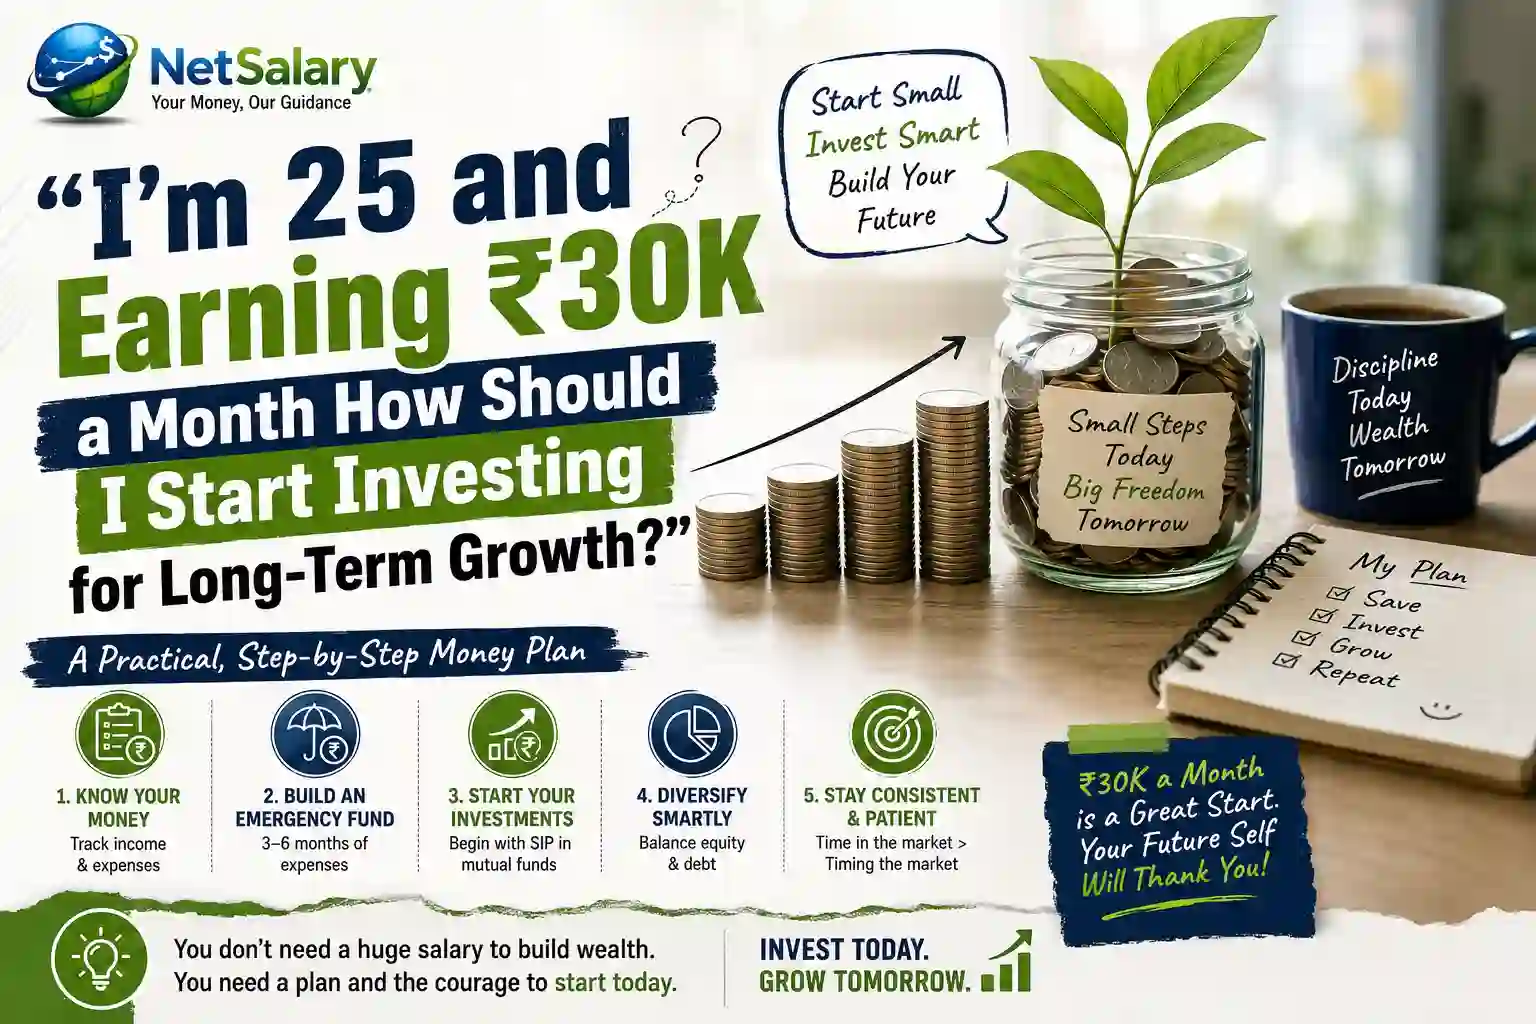
“I’m 25 and earning ₹30k a month how should I start investi for long-term growth?” This is one of the most common questions young earners in India type into Google, usually late at night after payday, right after rent and a few EMIs have already eaten into the salary. The good news is that ₹30,000 a month is a perfectly workable starting point. You do not need a six figure salary to build wealth. You need a system, a bit of patience, and the willingness to start with whatever amount you can manage this month, even if it is small.
This guide is written specifically for someone in that exact position: 25 years old, take home pay of around ₹30,000, little to no investment experience, and a genuine desire to build long-term wealth instead of just surviving month to month. So let’s explore “I’m 25 and Earning ₹30K a Month How Should I Start Investing for Long-Term Growth?”
Why 25 Is Actually a Great Age to Start, Even on a Modest Salary
Most financial advice focuses on how much you invest. What actually moves the needle more, especially at your age, is how long that money stays invested.
Money invested in your twenties has three or four decades to grow before retirement. Money invested in your forties has half that runway. Because mutual fund and equity returns compound, meaning your gains generate their own gains year after year, the difference in outcome between starting at 25 and starting at 35 is far bigger than most people expect, even if the person who starts later invests more per month.
So the salary is not the limiting factor here. The habit is.
Step One: Get a Clear Picture of Where Your ₹30,000 Actually Goes
Before you open a single investment app, spend one week writing down every rupee you spend. Most people earning ₹30,000 a month have no idea how much is going toward food delivery, subscriptions, or small impulse purchases until they see it on paper.
A rough monthly split that works for a lot of people at this income level looks something like this:
| Category | Approximate Amount |
|---|---|
| Rent and utilities | Rs. 8,000 to Rs. 10,000 |
| Food and groceries | Rs. 4,000 to Rs. 5,000 |
| Transport | Rs. 1,500 to Rs. 2,000 |
| Phone and internet | Rs. 800 to Rs. 1,000 |
| Family support or EMI | Rs. 3,000 (if applicable) |
| Personal and lifestyle | Rs. 2,000 to Rs. 3,000 |
| Savings and investments | Rs. 5,000 to Rs. 6,000 |
This is only a template. Your actual city, rent, and family responsibilities will change these numbers. The point of the exercise is to know your number, the actual amount you can realistically invest every month without straining yourself into quitting the habit after two months.
Step Two: Build a Small Emergency Fund First
It is tempting to put every spare rupee into mutual funds right away because that feels like “real” investing. Resist that urge until you have a basic safety net in place.
An emergency fund exists for one reason: so that a job loss, a medical bill, or a broken laptop does not force you to break your investments or take an expensive personal loan.
For someone earning ₹30,000 a month, a realistic starting target is 3 months of essential expenses, roughly Rs. 40,000 to Rs. 60,000, held in:
- A separate savings account you do not touch casually
- A liquid mutual fund, which is slightly more tax efficient than a plain savings account for money you might need in a hurry
You do not need to build this fund before you invest a single rupee elsewhere. Many people split their surplus, for example putting 60 percent toward the emergency fund and 40 percent into a starter SIP, until the emergency fund is complete, and then redirecting everything into investments.
Step Three: Decide How Much You Can Actually Invest
A commonly used benchmark is investing around 15 to 20 percent of take home pay. On a ₹30,000 salary, that works out to roughly Rs. 4,500 to Rs. 6,000 a month.
If that number feels impossible right now, do not let it stop you from starting. Beginning with Rs. 1,000 or Rs. 2,000 a month and increasing it every time your salary goes up is far better than waiting for the “right” amount before you begin. The habit matters more than the figure in the first year or two.
Step Four: Understand SIPs Before Anything Else
A Systematic Investment Plan, or SIP, is simply an instruction to your mutual fund to automatically deduct a fixed amount from your bank account every month and invest it. It removes the guesswork of timing the market and builds the habit of investing automatically, similar to an EMI, except this one builds wealth for you instead of costing you money.
Here is a simplified example of how a modest SIP can grow, assuming an average return of around 11 to 12 percent a year over the long run, which is a reasonable historical range for diversified equity mutual funds in India, though actual future returns are never guaranteed:
| Monthly SIP | Time Period | Approx. Value at 12% |
|---|---|---|
| Rs. 2,000 | 20 years | Rs. 20 lakh |
| Rs. 4,000 | 20 years | Rs. 40 lakh |
| Rs. 5,000 | 25 years | Rs. 94 lakh |
| Rs. 10,000 | 25 years | Rs. 1.9 crore |
These are illustrative, not guaranteed figures. Markets go up and down. What stays constant is that starting early and staying consistent, especially not stopping SIPs during a market fall, is what makes these numbers realistic over long periods.
Where Should Rs. 5,000 a Month Actually Go?
For a beginner at this income level, a simple three way split works well and does not require constant monitoring:
- 60 percent in equity mutual funds, split between a Nifty 50 or Sensex index fund and a flexi cap or large and mid cap fund
- 20 percent in a debt or liquid fund, to keep building your safety cushion or fund medium term goals
- 20 percent in a tax saving instrument like an ELSS fund or PPF, if you are also looking to reduce your taxable income
Index Funds
These funds simply copy an index like the Nifty 50, so you get the average return of the top 50 companies in India without paying a fund manager to pick stocks. Costs are low, and for a first time investor, this simplicity is a genuine advantage rather than a limitation.
Flexi Cap or Multi Cap Funds
These invest across large, mid, and small companies, giving your portfolio a mix of stability and higher growth potential. A single well chosen flexi cap fund is often enough for a beginner’s core portfolio.
ELSS Funds
Equity Linked Savings Schemes come with a 3 year lock in and qualify for a deduction of up to Rs. 1.5 lakh a year under Section 80C (now Section 123 under the Income Tax Act, 2025) for those still on the old tax regime. If you have shifted to the new tax regime, this deduction does not apply to you, so check which regime you are actually filing under before assuming ELSS will save you tax.
PPF, for the Ultra Safe Portion
The Public Provident Fund currently offers 7.1 percent per annum, tax free, with a 15 year lock in. It is not exciting, but it is one of the few instruments in India where the return, the principal, and the maturity amount are all completely tax exempt. Even Rs. 500 a month keeps the account active, so it is worth opening early even if you can only contribute small amounts initially.
Do Not Ignore Insurance Just Because You Are Young
A single hospitalisation can wipe out a year of careful saving. Before you get excited about equity returns, make sure you have:
- A basic health insurance policy, separate from whatever your employer provides, since employer cover usually ends the day you leave the job
- A term life insurance policy, only if someone depends on your income financially, such as parents or a spouse. If nobody depends on you financially yet, this can wait
These are not investments and will not grow your money. Their job is to stop one bad event from undoing years of financial progress.
Habits That Matter More Than Fund Selection
Increase Your SIP With Every Raise
When your salary moves from Rs. 30,000 to Rs. 35,000 or Rs. 40,000, resist the urge to expand your lifestyle by the same margin. A simple rule that works well: put at least half of every raise directly into your SIP before you get used to spending it.
Watch for Lifestyle Creep
Small recurring expenses, food delivery, subscription apps, frequent online shopping, are the quiet reason many people never manage to invest, regardless of how much they earn. It is rarely one big purchase that derails a budget. It is a dozen small ones repeated every month.
Stay Away From High Cost Debt
Credit card debt and buy now pay later schemes typically carry interest rates far higher than anything your investments will earn. Paying off high interest debt is, in effect, a guaranteed return, so clear this before increasing your investment amount.
Common Mistakes to Avoid in Your First Few Years
- Investing without a goal. Are you investing for retirement, a home down payment, or general wealth building? The goal decides the fund type and time horizon.
- Chasing quick returns. Cryptocurrency hype, intraday trading tips from social media, and “guaranteed doubling” schemes are how many young investors lose money before they have even built real savings.
- Stopping SIPs when markets fall. A market correction actually means your fixed monthly amount buys more units at a lower price. Long-term investors who kept investing through past downturns generally came out ahead of those who paused.
- Checking your portfolio daily. Equity investing rewards patience, not attention. Reviewing your investments once a quarter is more than enough for a beginner.
A Simple Step-by-Step Way to Actually Start This Week
- Open a savings account if you do not already have one that is separate from your daily spending account.
- Complete your KYC using your PAN card and Aadhaar, which is now mandatory for any mutual fund investment in India.
- Choose one mutual fund platform, such as Groww, Zerodha Coin, Kuvera, or a direct plan through the fund house’s own app or website, to keep costs lower.
- Start your first SIP, even if it is just Rs. 500 to Rs. 1,000, in a Nifty 50 index fund or a well rated flexi cap fund.
- Set a calendar reminder to review your investments every three months, not every day.
What Financial Freedom Actually Looks Like
Financial freedom at this stage of life is rarely about becoming wealthy overnight. It looks more like not panicking when your phone breaks, being able to change jobs without fear because you have a cushion, and knowing that a portion of every salary is quietly working for your future without you having to think about it constantly.
Conclusion
If you are 25 and earning ₹30,000 a month wondering how to start investing for long-term growth, the honest answer is that your salary is not the obstacle people assume it is. What matters is opening an account this month, starting a SIP even if it is small, building a basic emergency fund, protecting yourself with health insurance, and letting time and consistency do the heavy lifting. The people who build real wealth from modest salaries are rarely the ones who found a clever trick. They are the ones who started early and did not stop.
FAQs
Is ₹30,000 a month enough to start investing?
Yes. Even Rs. 500 to Rs. 1,000 a month through a SIP is a valid starting point. The amount matters less than starting the habit early and increasing it as your income grows.
How much of my salary should I invest each month?
A commonly used guideline is 15 to 20 percent of take home pay, which works out to roughly Rs. 4,500 to Rs. 6,000 on a ₹30,000 salary. If that feels too high right now, start smaller and increase it gradually.
Should I save first or invest first?
Do both, but prioritise a small emergency fund of 3 months of expenses before you invest aggressively. You can build this fund and start a modest SIP at the same time by splitting your surplus.
What is the safest investment option for a beginner in India?
For long-term growth, index funds and diversified mutual funds through SIPs are considered relatively safer than individual stock picking for beginners. For guaranteed, tax free returns, PPF remains one of the safest options, currently offering 7.1 percent per annum.
Should I buy stocks directly or invest through mutual funds?
For a beginner, mutual funds through SIPs are generally more suitable since they are professionally managed and diversified. Direct stock picking usually works better once you have a few years of market understanding.
What happens to my investments if the market crashes?
Your SIP continues buying units at lower prices during a downturn, which historically benefits long-term investors. Stopping your SIP during a crash is usually the wrong move unless your goal itself has changed.
Do I need health insurance at 25 if I am healthy?
Yes. A single hospitalisation can cost lakhs of rupees and derail years of savings, regardless of your current health or age.
Is ELSS or PPF better for tax saving?
ELSS has a shorter lock in of 3 years and market linked returns, while PPF has a 15 year lock in with guaranteed, tax free returns. Many investors use both, ELSS for growth and PPF for stability, depending on their comfort with risk.
How long should I stay invested to see real growth?
Equity mutual funds generally need at least 7 to 10 years to smooth out market ups and downs and show meaningful compounding. Shorter time frames carry more risk of volatility affecting your returns.
What if my salary increases next year?
Increase your SIP amount along with your salary rather than only increasing your spending. Even directing half of every raise into investments compounds significantly over time.
Also check: 11 LPA In Hand Salary | 10.5 LPA In Hand Salary | 10 LPA In-Hand Salary | 9.5 LPA In-Hand Salary