

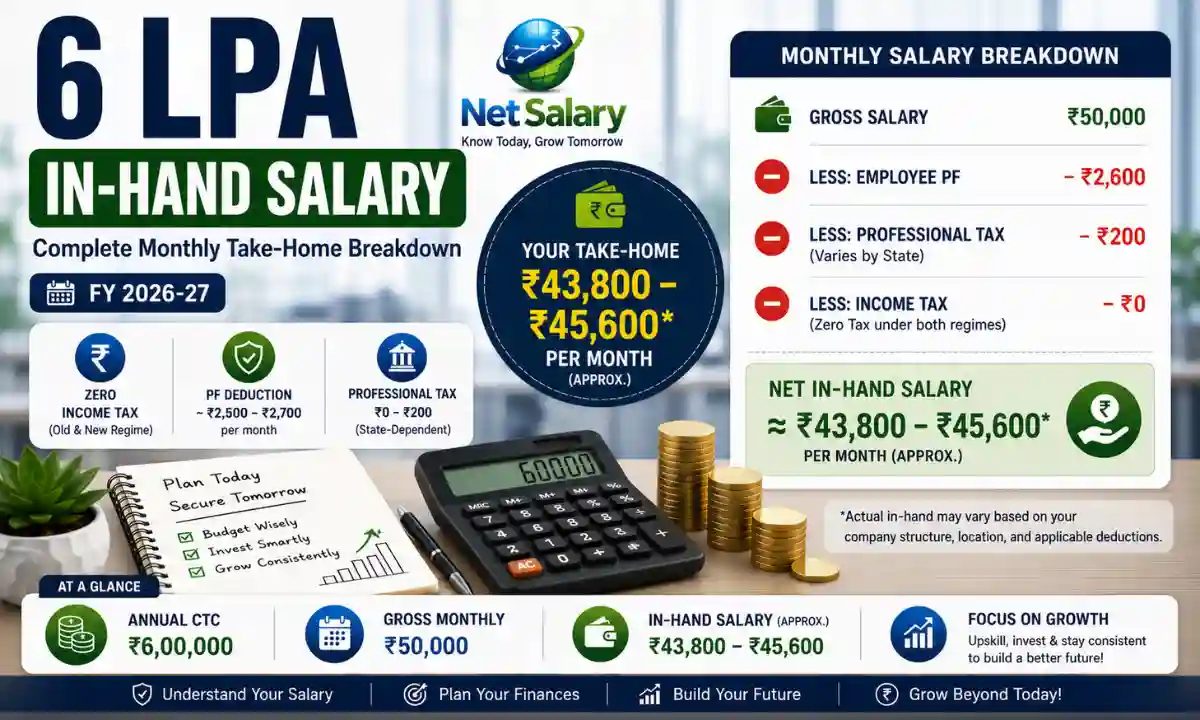
If your offer letter says 6 LPA (₹6,00,000 per annum), your realistic in-hand salary works out to roughly ₹45,000 to ₹48,000 per month under the New Tax Regime (the current default), depending on your company’s salary structure, your state’s professional tax rules, and whether Provident Fund (PF) is applicable. Under the New Tax Regime, income tax is ₹0 at this level. Under the Old Tax Regime, a small tax liability can apply unless you claim enough deductions to bring your taxable income down.
This article breaks down exactly how that number is calculated, what gets deducted, how it compares across cities, and how you can grow beyond this starting salary.
What Does “6 LPA” Actually Mean?
LPA stands for “Lakhs Per Annum.” So 6 LPA simply means your total annual package is ₹6,00,000. Companies almost always quote salaries as CTC (Cost to Company) – the full amount the employer spends on you in a year, not the amount that lands in your bank account.
CTC includes several things that never touch your monthly bank balance:
- Employer’s contribution to your Provident Fund
- Gratuity provision
- Group insurance premiums (if any)
- Annual bonus components (paid once a year, not monthly)
This is exactly why the number on your offer letter and the number that actually gets credited each month don’t match.
Gross Monthly Salary (Before Any Deductions)
The simplest math first:
₹6,00,000 (Annual CTC) ÷ 12 months = ₹50,000 per month (Gross)
This ₹50,000 is your gross monthly salary – the figure before PF, professional tax, or any other deduction is applied. Your actual in-hand salary will be a little lower than this.
Typical Salary Structure for a 6 LPA Package
Indian companies usually break CTC into multiple components. Here’s how a standard 6 LPA package is typically structured:
| Salary Component | Approximate Monthly Amount |
|---|---|
| Basic Salary (≈50% of CTC) | ₹25,000 |
| House Rent Allowance (HRA) | ₹12,500 |
| Special Allowance / Other Allowances | ₹9,500 |
| Employer PF Contribution (12% of Basic) | ₹3,000 (part of CTC, not paid to you directly) |
| Gratuity Provision | ~₹1,000 (part of CTC, paid only after 5 years of service) |
| Gross Monthly Salary | ₹50,000 |
Note: exact percentages vary by company. Some organisations don’t split Basic/HRA rigidly and instead pay a more consolidated fixed pay structure, especially in startups and mid-sized firms.
Deductions From a 6 LPA Salary In Hand
1. Income Tax – Depends on the Regime You Choose
This is the one place a 6 LPA salary differs from lower brackets, since it sits right at the edge of the Old Regime’s rebate limit:
| Tax Regime | Rebate Threshold (Section 87A) | Standard Deduction | Taxable Income on ₹6,00,000 CTC | Tax Payable |
|---|---|---|---|---|
| New Tax Regime (default since FY 2024-25) | Full rebate up to ₹12,00,000 taxable income | ₹75,000 | ₹5,25,000 (well within rebate limit) | ₹0 |
| Old Tax Regime | Full rebate up to ₹5,00,000 taxable income | ₹50,000 | ₹5,50,000 (exceeds rebate limit) | ≈ ₹23,400/year (≈ ₹1,950/month) |
Under the New Tax Regime, which is the default option since FY 2024-25 unless you actively opt out, your taxable income stays comfortably within the Section 87A rebate limit, so no TDS is deducted at all. Under the Old Tax Regime, your taxable income of ₹5,50,000 crosses the ₹5,00,000 rebate threshold, so a small tax liability applies unless you claim enough deductions (under Section 80C, 80D, HRA exemption, etc.) to bring your net taxable income back to ₹5,00,000 or below.
Practical takeaway: Most 6 LPA earners are better off with the New Tax Regime unless they have substantial investments (PPF, ELSS, life insurance, home loan interest) that would meaningfully reduce their taxable income under the Old Regime.
2. Employee Provident Fund (EPF) – Around ₹2,900 to ₹3,000/month
- EPF is deducted at 12% of Basic Salary.
- It is mandatory only for organisations with 20 or more employees, as per EPFO rules.
- Smaller companies and startups sometimes don’t deduct PF at all, especially for roles hired on a fixed consolidated pay structure.
- If PF is applicable: 12% of ₹25,000 (Basic) = ₹3,000/month goes into your EPF account (this builds your retirement corpus and isn’t “lost” money – you can withdraw it later or transfer it when you switch jobs).
3. Professional Tax – ₹0 to ₹200/month (State-Dependent)
Professional tax is a small state-level tax, and it varies:
| State | Approx. Professional Tax (Monthly) |
|---|---|
| Maharashtra | ₹150 – ₹200 |
| Karnataka | ₹200 |
| West Bengal | ₹110 |
| Delhi | ₹0 (not applicable) |
| Uttar Pradesh | ₹0 (not applicable) |
| Gujarat | ₹150 – ₹200 |
If your state doesn’t levy professional tax, this deduction simply doesn’t apply to you.
4. ESIC (Employee State Insurance) – Not Applicable
ESIC applies only when gross monthly salary is below ₹21,000. Since a 6 LPA package gives a gross monthly salary of ₹50,000, this deduction does not apply.
Final In-Hand Salary Calculation
Putting it all together under the New Tax Regime (the current default):
| Item | Amount (Monthly) |
|---|---|
| Gross Salary | ₹50,000 |
| Less: Employee PF | – ₹3,000 |
| Less: Professional Tax | – ₹150 (varies by state) |
| Less: Income Tax | – ₹0 |
| Net In-Hand Salary | ≈ ₹46,850 |
Net In-Hand Salary: ₹46,850
Realistic range: Depending on whether PF applies, your state’s professional tax, and your company’s exact structure, your 6 LPA in-hand salary typically falls between ₹45,000 and ₹48,000 per month under the New Tax Regime. If you opt for the Old Tax Regime without sufficient deductions, expect roughly ₹1,900-₹2,000 less per month due to income tax.
Example: How Two Different Companies Pay the Same 6 LPA Salary In Hand
Example A – A mid-sized company with PF and professional tax (Maharashtra), New Regime:
- Gross: ₹50,000
- EPF: -₹3,000
- Professional Tax: -₹200
- Income Tax: -₹0
- In-hand: ₹46,800
Example B – A smaller firm, no PF deducted, Delhi-based (no professional tax), New Regime:
- Gross: ₹50,000
- EPF: -₹0
- Professional Tax: -₹0
- Income Tax: -₹0
- In-hand: ₹50,000
This shows why two people with the “same” 6 LPA offer can receive noticeably different amounts in their bank account. The difference comes entirely from PF applicability and state tax rules, not from hidden charges. Always ask HR for a detailed salary breakup before accepting an offer, rather than relying on the CTC figure alone.
Old Tax Regime vs New Tax Regime at 6 LPA Salary In Hand
| Factor | Old Regime | New Regime |
|---|---|---|
| Rebate threshold (Section 87A) | Taxable income up to ₹5,00,000 | Taxable income up to ₹12,00,000 |
| Standard deduction | ₹50,000 | ₹75,000 |
| Section 80C, 80D deductions available | Yes | No (mostly) |
| Tax payable on ₹6,00,000 CTC | ≈ ₹23,400/year (without deductions) | ₹0 |
| Recommended for 6 LPA earners | Only if you can claim ₹50,000+ in deductions (80C, 80D, HRA) to bring taxable income to ₹5,00,000 or below | New Regime (simpler, higher rebate ceiling) |
Practical takeaway: At 6 LPA, the New Tax Regime is almost always the better default choice, since it results in zero tax without requiring any investment proofs or paperwork. The Old Regime only makes sense if you already have significant 80C investments (PF, PPF, ELSS, life insurance) or a home loan that would push your taxable income below ₹5,00,000.
Should You File an Income Tax Return (ITR) at 6 LPA?
Filing an ITR is strongly recommended, even if your tax liability under the New Regime is nil:
- Loan applications (personal loans, car loans, home loans, credit cards) almost always require ITR as income proof.
- Visa applications for international travel or higher studies frequently ask for ITR records.
- Building a financial history that becomes essential as your income and financial needs grow.
- If you’re on the Old Regime and owe tax, filing your ITR on time also helps you avoid penalties and interest under the Income Tax Act.
Is 6 LPA a Good Salary in India?
A 6 LPA salary is generally considered a strong early-to-mid career package, typically associated with:
- Graduates with 2-4 years of relevant work experience
- Mid-level roles in IT, banking, marketing, consulting, and operations
- A competitive package in fields like core engineering, analytics, or finance
- Employees in Tier-2/Tier-3 cities, where it supports a genuinely comfortable, even upper-middle-class lifestyle
City-Wise Comfort Level
| City Tier | Comfort Level on 6 LPA | Typical Living Arrangement |
|---|---|---|
| Metro (Mumbai, Delhi, Bangalore) | Comfortable, independent living becomes realistic | Independent 1BHK or shared 2BHK |
| Tier-2 (Jaipur, Lucknow, Indore) | Very comfortable with strong savings | Independent 1-2BHK |
| Tier-3 (smaller towns) | Highly comfortable | Independent living, significant savings possible |
In metro cities, ₹47,000/month supports independent living in a 1BHK or a shared 2BHK, along with decent lifestyle spending and reasonable savings. In Tier-2 and Tier-3 cities, the same amount supports a genuinely comfortable lifestyle with strong monthly savings or investments.
Sample Monthly Budget on 6 LPA In-Hand (₹46,850)
| Expense Category | Approx. Amount |
|---|---|
| Rent (independent 1BHK or shared 2BHK) | ₹10,000 – ₹15,000 |
| Food & Groceries | ₹6,500 – ₹8,000 |
| Transport | ₹2,500 – ₹3,500 |
| Mobile/Internet | ₹800 |
| Miscellaneous & Lifestyle | ₹3,500 – ₹4,500 |
| Savings & Investments | ₹11,000 – ₹14,000 |
This budget is realistic across most cities, with metro residents likely spending more on rent and Tier-2/3 residents having room for higher savings.
How to Grow Beyond a 6 LPA Salary
A 6 LPA package is a strong platform to build from. Here’s how professionals typically move up:
- Upskill continuously – specialised certifications in cloud computing, data analytics, product management, or digital marketing can open doors to significantly higher-paying roles.
- Switch jobs strategically – a job change after 2-3 years of experience often brings a 30-50% salary hike, usually higher than an internal annual increment.
- Take on more responsibility – moving into team lead, senior analyst, or specialist roles within your current organisation can accelerate salary growth.
- Build a strong professional network – referrals remain one of the most effective ways to access better-paying roles.
- Aim for measurable growth – many professionals move from a 6 LPA package to 10-14 LPA within 3-5 years with consistent effort and the right career moves.
6 LPA vs Other Common Salary Levels (Quick Comparison)
| CTC | Approx. Monthly In-Hand | Income Tax Payable (New Regime) |
|---|---|---|
| 4.5 LPA | ₹34,000 – ₹36,500 | ₹0 |
| 5 LPA | ₹38,000 – ₹41,000 | ₹0 |
| 5.5 LPA | ₹41,500 – ₹44,000 | ₹0 |
| 6 LPA | ₹45,000 – ₹48,000 | ₹0 |
| 8 LPA | ₹58,000 – ₹62,000 | Minimal |
Key Takeaways
- 6 LPA CTC = ₹6,00,000/year, giving a gross monthly salary of ₹50,000.
- Real in-hand salary is approximately ₹45,000-₹48,000/month under the New Tax Regime, after PF and professional tax deductions.
- Income tax is zero under the New Regime, but the Old Regime can attract roughly ₹1,900-₹2,000/month in tax unless you claim sufficient deductions.
- PF deduction (if applicable) is roughly 12% of Basic Salary, and only mandatory for companies with 20+ employees.
- Professional tax varies by state, ranging from ₹0 to ₹200/month.
- ESIC does not apply at this salary level since gross monthly salary comfortably exceeds the ₹21,000 threshold.
- Filing an ITR is strongly advisable regardless of tax liability, for future loans, visas, and financial credibility.
- A 6 LPA salary supports a genuinely comfortable, even upper-middle-class lifestyle in most Indian cities.
FAQs
What is the in-hand salary for 6 LPA per month?
The in-hand salary for a 6 LPA package is typically between ₹45,000 and ₹48,000 per month under the New Tax Regime, depending on PF applicability and state-specific professional tax.
Is there any income tax on a 6 LPA salary?
Under the New Tax Regime, no. Taxable income after standard deduction stays within the Section 87A rebate limit, so tax is zero. Under the Old Tax Regime, a small tax of roughly ₹23,400/year can apply unless you claim enough deductions to bring taxable income to ₹5,00,000 or below.
What deductions apply to a 6 LPA salary?
The main deductions are the Employee PF contribution (around 12% of Basic Salary, roughly ₹2,900-₹3,000/month, if applicable) and Professional Tax (₹0-₹200/month depending on the state). Income tax may also apply under the Old Regime.
Is PF mandatory on a 6 LPA salary?
PF is mandatory only if the employer has 20 or more employees, as per EPFO rules. Some smaller companies structure salaries without PF deduction.
Should I choose the Old or New Tax Regime at 6 LPA?
The New Regime is usually better, since it results in zero tax without any paperwork. The Old Regime only makes sense if you already have significant 80C/80D investments or a home loan that brings your taxable income below ₹5,00,000
Should I file an ITR if my salary is 6 LPA?
Yes, it’s strongly recommended regardless of your tax liability, as it helps with loan approvals, visa applications, and building a financial record for the future.
Conclusion
A 6 LPA salary translates to a monthly in-hand salary of roughly ₹45,000 to ₹48,000 under the New Tax Regime, which results in zero income tax liability at this income level. The gap between the ₹50,000 gross monthly figure and your actual take-home comes mainly from Provident Fund contributions (if applicable) and state professional tax. If you choose the Old Tax Regime without adequate deductions, expect a small additional tax deduction of around ₹1,900-₹2,000/month.
A 6 LPA package marks a genuinely comfortable stage in most professionals’ careers, supporting independent living in metros and a strong, upper-middle-class lifestyle in Tier-2 and Tier-3 cities. With continued upskilling, timely job switches, and disciplined financial planning, this is a solid base from which to build toward significantly higher income in the years ahead.
Also check: 5.5 LPA In Hand Salary | 4.5 LPA In Hand Salary | 3.5 LPA In Hand Salary | 5 LPA In Hand Salary